





A recent meeting with G7 leaders resulted in 100 million barrels of diesel and oil to be shared from reserves, following threats of oil embargoes and further price rises.
Diesel and oil crisis: Is your business preparing for the unexpected?
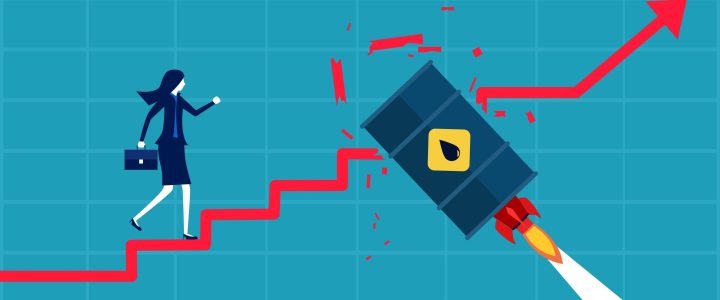
A recent meeting with G7 leaders resulted in 100 million barrels of diesel and oil to be shared from reserves, following threats of oil embargoes and further price rises.

In late September, Andy Burnham announced a £210 million cash injection into high street regeneration to convert vacant, derelict buildings into cafes and community hubs.
According to the latest Hiscox Cyber Readiness Report, almost two in five small businesses in the UK suffered a successful cyber-attack in the last year, with each attack costing an average of £26,650.
Globally, cyber incidents cause around 32 hours of operational disruption a year on average.
Cyber-attacks are no longer exceptional events, being viewed more as recurring costs, so businesses must prepare themselves financially for the impact.
How should you prepare your finances in advance of a cyber-attack?
A cyber-attack is slowly and sadly becoming a reality for many SME owners across the UK.
To prepare, business owners should assess the potential financial risk a cyber-attack poses and forecast cash flow to ensure their business can survive one.
It could also be beneficial to value your data assets to estimate the worth of any lost revenue and recovery expenses.
Business owners may also want to keep offline playbooks. These are secure, printed offline copies of critical financial contacts, account numbers and recovery protocols to ensure that your business has key information in the event of a cyber-attack.
Additionally, your business should establish strict double-check procedures for unusual payment requests or changes to supplier details to prevent business email compromise.
You should also factor cyber insurance premiums into your operational risk management to ensure that you are prepared for any eventuality.
What should you do to get your finances back in check after a cyber-attack?
Should the worst-case scenario happen, once you are back on track, the first thing you should do is speak with your accountant.
Your accountant will help you to calculate the exact monetary value of damaged assets, lost revenue and stolen money so that you know exactly where your business stands.
They will then review your financial data and your tax records to establish a baseline for recovery and determine if the business can continue or if restructuring is necessary.
Accountants can also help during complex cyber insurance claims by submitting the required evidence to ensure fair financial assessments of the business interruption costs.
Once you have received any insurance payments, an accountant can advise on the tax implications.
How can we help?
Cyber-attacks are becoming more prevalent for businesses up and down the UK.
That is why it is imperative that you receive advice on how you can best prepare your finances in a worst-case scenario.
Our team of accountants can help you to prepare your business for a cyber-attack and in the event of a cyber-attack, we can help you pick up the financial pieces.
Get in touch with our team for support with preparing your business for a cyber-attack.
According to UK Finance, gross lending to SMEs from the main high street banks reached £5.35 billion in the second quarter of 2026, the highest quarterly level recorded since the pandemic.
Real estate and professional service firms drove much of this growth, while manufacturers and hospitality businesses borrowed less.
How can loans help SMEs?
A loan can often be a lifeline for SMEs in a financial rough patch. It can help a business bridge cash flow gaps in the short term, ensuring that it has enough money to cover payroll, rent and supplier obligations.
It could also be the case that a loan can help to fund expansion to increase business opportunities or hire more staff.
Additionally, loans can help business owners to retain ownership of the company rather than selling equity to investors.
However, SMEs need to remember that a loan must be paid back with interest regardless of business performance.
How should SMEs prepare for a loan?
Preparing your business for a loan can often be a tricky process. First, you will need to gather two to three years of profit and loss statements alongside cash flow forecasts and up-to-date tax filings.
Next, you will have to check and correct any errors that may be on your personal or business credit reports in order to optimise your credit profile before borrowing.
You will then have to create a strong business plan outlining your core growth strategy and market opportunity.
There should be a clear breakdown of how the funds will be used, linking every borrowed pound to revenue generation, as well as a risk mitigation section addressing potential economic downturns.
You must consider the lender that you are selecting by comparing criteria across high street banks and alternative providers.
How can an accountant help?
An accountant can be one of your most valuable assets when applying for finance. They can help to improve your financial record-keeping, build advanced financial models and stress-test your cash flow to give lenders greater confidence in your business.
We understand that it is tough for SMEs to obtain funding at the moment. That is why our team can help you obtain the loan that you need.
For support with accessing loans, get in touch with our team.
The Department for Business, Innovation, Science and Trade (DBIST) initiated a ‘modernising corporate reporting’ consultation on 7 September 2026, which closes on 30 November 2026.
Under the proposed overhauls, many medium-sized companies may be exempt from mandatory audits.
This consultation forms part of a wider Government pledge to cut administrative burdens on businesses by 25 per cent by 2029.
What is being proposed?
The Companies Act 2006 considers various company size categories to assess which reporting, audit and disclosure requirements apply.
For medium-sized businesses wanting to access exemptions currently exclusive to small companies, they must not exceed two of the following three thresholds:
Under these exemptions, many businesses would no longer need to have an audit, provide cash flow statements or prepare consolidated accounts.
Elsewhere, the proposals from DBIST include:
Is it always smart to forgo an audit?
While the proposals mean audits may become optional for some SMEs, forgoing an audit isn’t always the smartest move.
An audit can often go one step further than simple compliance and financial reporting, providing insights and peace of mind that your numbers are accurate.
Lenders also often rely on audited accounts when deciding how much to lend and at which interest rate.
Likewise, when it comes to selling a business, buyers and investors often look at audited figures when conducting due diligence as they offer greater credibility.
For any businesses mulling the exemption, it is important to evaluate long-term plans and whether spending money on an audit could have benefits.
At the moment, these changes are part of an ongoing consultation and so may be subject to change in future. We will bring you further updates as they emerge.
Speak to an accountant to evaluate whether an audit may be beneficial to your business.
The so-called mansion tax is already beginning to have an impact on the UK housing market, despite the surcharge not being due to come into effect until April 2028.
Under the new tax, formally known as the High Value Council Tax Surcharge, homes in England worth £2 million or more, based on their value as of April 2026, will face an annual charge on top of their council tax.
Some sellers appear to be pricing homes just under £2 million to attract buyers who want to avoid paying the incoming council tax surcharge.
How is the housing market changing?
According to a report by Tax Policy Associates, sales at exactly £2 million made up 2.70 per cent of completed sales between £1.7 million and £2.3 million from December 2025 to July 2026, down from 5.69 per cent in the same period a year earlier.
At the same time, the share of sales priced within £10,000 below the mansion tax threshold rose roughly fivefold, from 0.44 per cent to 2.27 per cent.
Tax Policy Associates describes this as clear evidence of prices bunching below the threshold, although it has not yet found evidence of a wider fall in property values.
The annual surcharge bands are as follows:
What are the risks with an artificially low property price?
While sellers can distort their asking price in an attempt to avoid the tax, the Valuation Office is expected to use comparable sales and property characteristics to assess which properties sit above the £2 million threshold.
This means tax liabilities will depend on assessed value, calculated using a combination of sales data and technology-driven modelling, rather than simply what a property is sold for.
Therefore, sellers who artificially drop their price to below the threshold may not achieve the intended tax outcome, as the buyer may still be liable to pay the surcharge.
Buyers and sellers may try to make up the costs elsewhere, such as inflated payments for furniture or fixtures, but this is also risky.
As Stamp Duty Land Tax is levied on property transactions, HMRC scrutinises extra charges to determine if they are just and reasonable and at fair market value.
If they are deemed to be disproportionate, the buyer may face extra tax and even interest and penalties.
Reforms to the Benefits in Kind (BIK) system have continued to change in recent years, as the Government prepares to roll out mandatory payrolling.
From April 2027, businesses will be required to payroll BIK, but this will now be a phased approach, with the full reforms in place from April 2028.
For employers who were expecting to do away with the P11D process in the main from next year, this means that most will still need to complete and submit P11Ds for 2026/27 and, for any benefits not yet payrolled, for 2027/28.
The new phased approach to payrolling BIK
HMRC confirmed earlier this year that in April next year, employers will only need to payroll BIK for the following benefits:
From this date, Income Tax and employer National Insurance Contributions (NICs) on these benefits must be paid using the same real-time system as the rest of PAYE.
HMRC intends its Real Time Information (RTI) system to handle the payrolling of most BIK from April 2028.
The exceptions are employment-related beneficial loans and living accommodation.
Employers providing either of these will still need to complete P11Ds for the relevant employees each year.
HMRC is also weighing up whether to keep P11Ds for a small number of specific situations, such as internationally mobile employees on modified payroll arrangements. We are still waiting for HMRC to publish further details on this.
For 2028/29, every other benefit must be processed through your payroll, with the associated Income Tax and Class 1A National Insurance paid in real time.
What is the expected impact of the changes?
First and foremost, you will need to prepare your payroll processes to incorporate real-time reporting of BIK.
This should be relatively straightforward, but it still makes sense to ensure your team and systems are prepared.
You will need to report more information than before, on a more regular basis, which may lead to more payroll errors, so don’t leave preparations too late.
In the first year of payrolling BIK, there may also be cash flow implications for the business and employees.
In 2027/28, an employer will pay the final P11D-based Class 1A bill for 2026/27 in July 2027. In the same year, it will also pay Class 1A on 2027/28 benefits in real time. That’s roughly two years’ worth of Class 1A leaving the business within one year.
For employees, the same doubling up can happen, as the tax on benefits reported on a P11D is often collected after the event through Self Assessment the following January or through a tax code adjustment in a later year that recovers an underpayment.
In the first year of payrolling, an employee could still be paying off the previous year’s benefit tax while also having tax on their current benefits deducted from each pay packet.
Need help with the upcoming BIK reforms?
Businesses are being encouraged to act early on these changes to ensure they understand the cash flow implications and reporting rules of this new mandatory payroll requirement.
We are now just over six months away from the long-anticipated reforms to Inheritance Tax (IHT), which will see unspent pensions included within a person’s estate from April 2027.
First announced all the way back in the 2024 Autumn Budget, the move is expected to result in 10,500 more estates becoming liable for IHT in the 2027/28 tax year.
The changes will also mean that 38,500 estates will pay a higher IHT amount than under current rules.
Uncertainty over IHT treatment of pensions has also fuelled a surge in withdrawals. Financial Conduct Authority data shows the total value withdrawn from pensions reached £91.2 billion in 2025/26, up 70 per cent from £53.6 billion two years earlier.
What do the reforms to Inheritance Tax mean?
From 6 April 2027, most unused pension funds and death benefits will count as part of your taxable estate for IHT.
Thankfully, spouses, civil partners and registered charities remain exempt from IHT on inherited pension funds, but the beneficiaries of a couple’s combined estate will face tax on any pensions that push the value of their inheritance above the current thresholds.
With the IHT nil-rate band remaining frozen at £325,000 and the residence nil-rate band of £175,000 also remaining unchanged until April 2031, this change is going to affect many families in future.
As you can see from the level of withdrawals that have already taken place, some people are acting early to reduce the size of their pension and their taxable estate.
What can I do to reduce the risk of an Inheritance Tax bill?
More people are dipping into their pension savings and this trend points to one practical measure available to anyone concerned about IHT.
Most UK savers are able to draw a quarter of their pension pot without paying tax once they reach 55. From 6 April 2028, that minimum age moves up to 57.
The amount that can be taken tax-free is capped at £268,275. Drawing a lump sum up to this figure can help people meet growing living costs, although this will only reduce the estate they leave behind if the money is spent or gifted. Cash that is withdrawn and left in a bank account still counts towards your estate for IHT.
Taking money out also opens the door to passing wealth on to family sooner than you might otherwise have intended.
Timing matters here, as if you die within seven years of making a gift, it may still count towards your estate for IHT purposes.
It is also worth pausing before treating a pension withdrawal as the obvious answer.
While it can cut your potential IHT exposure, it leaves you with a much smaller pension pot and gives up the investment growth that money might otherwise have achieved.
This is not a straightforward choice and it is one you need to be confident about before acting.
Get tax and financial advice before dipping into your pension
If you are concerned about the impact that your pension may have on your IHT bill in the future, then it is important to seek advice.
Speaking with a tax adviser, alongside an independent financial adviser, can help you to balance your retirement needs against a future tax liability for the beneficiaries of your estate.
If you would like guidance ahead of these changes in 2027, please speak to our team.
HMRC is currently sending out letters to people conducting consultancy work in the medical sector in an effort to close part of the tax gap.
Bookkeeping is often the least favourite task for business owners, but it remains essential. Read more