New tax rules on holiday lets – What does it mean for owners?

New tax rules on holiday lets – What does it mean for owners?

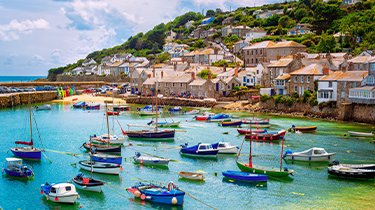
It was recently announced that the Government would reform business rates relief for owners of second homes – resulting in some holiday let owners facing additional costs of up to £1,000 a year.

The Department for Housing, Communities and Local Government wants to close what it sees as a loophole in the current business rates system that prevents some second homeowners from paying council tax.

Michael Gove, Secretary of State for Housing, Communities and Local Government, confirmed that new rules next year will only allow second homeowners to register for business rates relief if they can prove they rent out their properties for at least 70 days per year.

What exactly is changing?

As the rules stand, second homeowners pay business rates, which are cheaper than council tax, if they make their property available for letting for 140 days in the coming year.

But once the change takes place in April next year, homeowners will have to prove they are let for at least 70 days a year or be forced to pay council tax instead.

Is the change necessary?

The move comes following a surge in the number of holiday lets in England, with around 65,000 residential units currently registered, up from 50,960 in 2019.

The Department for Levelling Up, Housing and Communities (DLUHC) also says that there is currently ‘no requirement’ to produce evidence that a second home has been let out – not just left empty.

The DLUHC says the move would protect ‘genuine’ small holiday letting businesses and ensure second-home owners paid a ‘fair’ contribution towards public services.

Mr Gove’s plans come after a consultation launched in 2018 and threats last year by the Treasury to close the loophole.

According to reports, the number of holiday lets in England has been increasing year on year from 50,960 in 2019 to 65,000 now.

The COVID pandemic is said to have fuelled the trend, as London and other city dwellers sought to escape to the countryside.

If your property portfolio is potentially affected by this change, please get in touch to find out how we can help you.

Link: Gove closes tax loophole on second homes

Company directors banned for Bounce Back Loan fraud

Company directors banned for Bounce Back Loan fraud

Two company directors have been banned for a total of 21 years after they fraudulently claimed £100,000 in bounce back loans.

Following an investigation by the Insolvency Service, Aamer Aslam from Huddersfield and Razwan Ashraf from Keighley were disqualified for 11 and 10 years respectively after they fraudulently claimed Bounce Back Loans (BBL).

The disqualifications prevent both from directly, or indirectly, becoming involved in the promotion, formation, or management of a company, without the permission of the court.

The duo were co-directors of Scholars Academy Ltd, which is a specialist tuition centre for children in West Yorkshire.

In May 2020 Aslam applied for a BBL by providing an estimated company turnover of £200,000. Scholars received the loan of £50,000 but went into voluntary liquidation in January 2021, which triggered the investigation by the Insolvency Service.

At the time of liquidation, the directors listed the company’s liabilities to the bank as £7,000, but the bank later notified the liquidator that it was owed £50,000 by the company due to the BBL.

The investigation found that the duo was inflating the company’s turnover with Scholars’ bank statements actually showing a maximum monthly income of just £640, which means their turnover was only £7,680 and did not meet the criteria to apply for a BBL.

It was also found that Aslam and Ashraf used the money to make monthly payments to four family members of Ashraf. All four received £2,000 a month after the duo received the loan money.

Aslam and Ashraf told the Insolvency Service that these payments were genuine business expenses, but they were unable to provide evidence to support this.

Alongside this, Ashraf was also the sole director of another educational company, Progress First Ltd, and in May 2020 he applied for a BBL and fraudulently declared in the application form that annual turnover in 2019 was £200,000, when Progress’ bank statements showed that turnover was £38,973.

This resulted in Progress receiving the full loan of £50,000, when it would only have been entitled to a loan of £9,927.

Ashraf claimed that the money was used to pay for company expenses, however, regular payments were made to three individuals, and no evidence was produced to show that these payments were genuine business expenditures.

Ashraf has since repaid £35,000 to the liquidator to settle claims against him for the Progress loan, and a further £25,000 in settlement of claims against both directors about the loans taken out by Scholars.

COVID crackdown

This is the latest in a number of bans issued by the Insolvency Service against directors who have misused the COVID support schemes.

The Insolvency Service has been given new powers to investigate, disqualify and potentially prosecute company directors who abuse the company dissolution process.

The Rating (Coronavirus) and Directors Disqualification (Dissolved Companies) Act will also help tackle directors dissolving companies to avoid repaying Government-backed loans taken out during the Coronavirus pandemic.

Under the terms of the Act, the Insolvency Service, on behalf of the Business Secretary, will be able to investigate and tackle ‘unfit’ directors who place their firm in administration to avoid paying subcontractors and suppliers.

If misconduct is found, directors can face sanctions, including being disqualified as a company director for up to 15 years or, in the most serious of cases, prosecution.

The Business Secretary will also be able to apply to the court for an order to require a disqualified director of a fraudulently dissolved company to pay compensation to creditors who have lost out due to their actions.

In addition, the Insolvency Service will be able to investigate live companies where there is evidence of wrongdoing, such as misuse of COVID support.

Our team at Clemence Hoar Cummings are ready to support directors targeted by HMRC and the Insolvency Service’s ongoing COVID support crackdown. To find out how we can help, please speak to us.

Link: Bans for two directors who abused Bounce Back Loan scheme

Fears over move to MTD, as few take part in income tax pilot scheme

Fears over move to MTD, as few take part in income tax pilot scheme

A pilot scheme using software in preparation for the next phase of HM Revenue & Customs’ (HMRC) Making Tax Digital (MTD) initiative has seen a slump in users.

Self-employed businesses and landlords with annual business or property income above £10,000 will need to follow the rules for MTD for Income Tax and Self-Assessment (ITSA) from 6 April 2024.

Some businesses and agents are already keeping digital records and providing updates to HMRC as part of the live pilot project to evaluate and develop the MTD service for ITSA.

However, research reported in the Financial Times has discovered that only nine people are currently taking part in the trial, a figure confirmed by HMRC.

The number peaked at around 900 users in the 2018-2019 period and may have since been affected by the pandemic.

Many accountants are now concerned that the system, which covers 4.3 million self-employed businesses, partnerships, and landlords, many of whom will be unaware of what is happening, may not be ready for the switchover.

Currently the self-employed must file just one end-of-year tax return but MTD ITSA will involve having to submit updates quarterly every three months and an end-of-year statement, plus a “finalisation return” (now called a tax return) each year. This means six reports to HMRC in total replacing the current single annual Self-Assessment tax return.

On top of this, the self-employed and landlords will have to license accounting software from approved providers, with the Government offering discounts of up to £5,000 for small businesses to rent software.

If you need help with MTD we are here to assist you. To find out more about our dedicated digital tax and cloud accounting services contact us.

Link: Just nine people trialling digital tax for self-employed

Nearly half a million SMEs at risk of failing due to late payments crisis

Nearly half a million SMEs at risk of failing due to late payments crisis

According to a new survey from the Federation of Small Business (FSB), more than 440,000 small businesses could fail because of a new late payment crisis.

The national small business organisation has called for the Government to step in and take urgent action to improve how companies are paid.

According to the FSB study, 30 per cent of small businesses have seen the late payment of invoices increase over the last three months, of which almost eight per cent said that the problem was so bad that it might force them to close.

While smaller companies wait to get paid, they must continue to pay their suppliers, tax bills and staff wages.

The effect of persistent overdue payment problems is that it has a ripple effect throughout the wider economy, forcing other companies to close their doors as well.

The FSB estimates that more than 400,000 small firms have shut during the pandemic, with late payments being a key factor in the failure of many companies. However, it predicts that up to 440,000 SMEs may be forced to close this year due to late payments.

FSB National Chair, Mike Cherry, said: “Late payment was destroying thousands of small businesses even before the pandemic hit – the pandemic has made matters worse. In the past, the Government has rightly identified greater board accountability as key to spurring change in this area, but delivery has been slow.”

The FSB wants to see every business and Government agency abide by the existing prompt payment code.

They argue that 30-day payment terms should be “the norm for those who are committed to environmental, social and governance best practice”.

However, it has gone further saying that every big UK corporation should have a dedicated director that is focused on improving payments to small businesses.

If you are struggling with late payments, then it is really important that you seek advice immediately. To find out how we can help improve your financial health monitoring and credit control procedures, please get in touch.

Link: UK’s late payment ‘crisis’ risks future of 440,000 small firms

Top tax tips to help your business save money

Top tax tips to help your business save money

Whether you are setting up a new business, or already have a successful, well-established company, there are many ways that you can save money through tax reliefs and allowances.

Certain tax initiatives even allow business owners to save money that can be invested in their company.

Enhanced Capital Allowance (ECA)

Enhanced Capital Allowance (ECA) schemes encourage businesses to invest in efficient technologies. The scheme lets your business claim 100 per cent first-year allowances, i.e., tax relief, on investments in certain technologies and products.

If you buy an asset that qualifies for first-year allowances you can deduct the full cost from your profits before tax.

You can claim first-year allowances in addition to the Annual Investment Allowance (AIA) – they do not count towards your AIA limit.

What qualifies

  • Some cars with low CO2 emissions
  • Energy-saving equipment that’s on the energy technology product list, for example, certain motors
  • Water-saving equipment that’s on the water-efficient technologies product list, for example, meters, efficient toilets and taps
  • Plant and machinery for gas refuelling stations, for example, storage tanks, pumps
  • Gas, biogas, and hydrogen refuelling equipment
  • New zero-emission goods vehicles.

You cannot normally claim on items your business buys to lease to other people or for use within a home you let out.

Annual Investment Allowance

This measure remains temporarily increased from £200,000 to £1,000,000 for qualifying expenditure on plant and machinery incurred during the period from 1 January 2022 to 31 March 2023.

This measure is intended to deliver positive outcomes for businesses by supporting and encouraging business investment, and by simplifying the tax relief for such investments.

R&D tax credits

You may be eligible for R&D tax credits, even if your small business is running at a loss.

The HM Revenue & Customs (HMRC) definition is broad, and you don’t have to be engaged in laboratory work to benefit from this incentive.

Software developers, architects and many other professionals have all successfully claimed R&D tax relief because of this incentive.

Repairs and renovations to property

The business renovation allowance will give SMEs a tax break.

If the building your business plans to use has been empty for more than a year and was previously used in a different capacity, you may be eligible for a 100 per cent tax incentive on any renovations you might carry out.

Reduce NICs with the Employment Allowance

You can claim Employment Allowance if you’re a business or charity and your employers’ Class 1 National Insurance liabilities were less than £100,000 in the previous tax year.

Employment Allowance allows eligible employers to reduce their annual National Insurance liability by up to £4,000.

You’ll pay less employers’ Class 1 National Insurance each time you run your payroll until the £4,000 has gone or the tax year ends (whichever is sooner).

You can only claim against your employers’ Class 1 National Insurance liability up to a maximum of £4,000 each tax year. You can still claim the allowance if your liability was less than £4,000 a year.

In some cases, a company can eliminate their Employer’s NIC bill as a result. Note, it is not possible to claim the allowance if your company only has one employee/director.

As the end of the tax year is nearly upon us, it is important to seek advice at the earliest opportunity to make sure you take full advantage of the reliefs and allowances available. Please speak to our tax team today for advice.

Excepted estates: what are the new Inheritance Tax reporting rules?

Excepted estates: what are the new Inheritance Tax reporting rules?

More estates will now fall within the scope of “excepted estates” legislation following changes to the rules this year, it has been confirmed.

It comes after amendments to the Inheritance Tax (Delivery of Accounts) (Excepted Estates) (Amendment) Regulations 2021 on 01 January 2022.

Under the changes, the threshold gross value of an excepted estate has been increased from £1 million to £3 million (with the total amount of property held in a single settlement being increased from £150,000 to £1 million in most cases), while the threshold of an excepted estate’s chargeable trust property has been increased from £150,000 to £250,000.

The limit on specified transfers in the seven years before death, meanwhile, has increased from £150,000 to £250,000.

It means that fewer estates will now be forced to submit full Inheritance Tax accounts as a condition of obtaining probate, significantly reducing the burdensome reporting requirements for non-taxpaying estates.

Estates that qualify for excepted estate status can use form IHT205, rather than form IHT400.

Commenting on the changes after they were announced last year, HM Revenue & Customs (HMRC) said: “The measure will reduce IHT reporting burdens for more than 90 per cent of non-taxpaying estates requiring probate or confirmation.”

The changes apply to deaths on or after 01 January 2022.

For more information on the specialist IHT tax planning advice we are able to offer your clients, please contact us.

Government is set to close tax loophole for second homeowners

Government is set to close tax loophole for second homeowners

The Government has announced its intention to close a tax loophole that could leave second homeowners facing higher bills.

Michael Gove, Secretary of State for Housing, Communities and Local Government, has confirmed that the Government will introduce new rules next year that will only allow second homeowners to register for business rates relief if they can prove they rent out their properties for at least 70 days per year.

Owners could face paying more than £1,000 a year under plans to close the loophole.

As the rules stand, second homeowners pay business rates, which are cheaper than council tax, if they make their property available for letting for 140 days in the coming year.

But once the change takes place in April next year, homeowners will have to prove they are let for at least 70 days a year or be forced to pay council tax instead.

The move comes following a surge in the number of holiday lets in England, with around 65,000 residential units currently registered, up from 50,960 in 2019.

The Department for Levelling Up, Housing and Communities (DLUHC) also says that there is currently ‘no requirement’ to produce evidence that a second home has actually been let out – not just left empty.

The DLUHC says the move would protect ‘genuine’ small holiday letting businesses and ensure second-home owners paid a ‘fair’ contribution towards public services.

Mr Gove’s plans come after a consultation launched in 2018 and threats last year by the Treasury to close the loophole.

According to reports, the number of holiday lets in England has been increasing year on year from 50,960 in 2019 to 65,000 now.

The Covid pandemic is said to have fuelled the trend, as London and other city dwellers sought to escape to the countryside.

Levelling Up Minister Chris Pincher replied: ‘We have committed to close the loophole in the business rate system.’

For help and advice on all aspects of property tax and support for your conveyancing clients, please get in touch with our expert team today.

Income tax basis periods – What unincorporated businesses need to know

Income tax basis periods – What unincorporated businesses need to know

All unincorporated businesses, including sole traders, the self-employed and trading partnerships, will be taxed on profits generated in the 12 months to 5 April (or 31 March) each year from 2024-25.

Here is what you need to know:

  • The Government has proposed changes that will move the tax basis period for all unincorporated businesses
  • This will affect sole traders, partnerships and LLP’s who do not have an accounting year-end at that date
  • It may cause additional tax to be payable
  • Extra tax due can be spread over up to five years or by using Time to Pay arrangements
  • Overlap relief that has been accrued can also be used to offset a larger tax bill
  • It will affect accounting periods from 6 April 2023, as there will be a transition period during 2023-2024 when all businesses will have their basis period moved to the end of the tax year.

These changes were meant to be brought in a year earlier but were delayed by the Government in September 2021 to give those businesses affected more time to prepare.

The current system

Currently, unincorporated businesses are taxed on profits arising in the accounting period ending in a given tax year.

By law, unincorporated businesses do not have to produce accounts. They are, therefore, free to choose any accounting date they like.

This means that a business’s profit or loss for a tax year is usually the profit or loss for the year up to the accounting date – this is known as the basis period.

Specific rules determine the basis period during the early years of trading. Where the accounting end date is not 5 April or 31 March, which is the equivalent of 5 April for the first three years of trade, the rules can create overlapping basis periods, which charge tax on profits twice and generate ‘overlap relief’, given when the business ceases.

As other forms of income such as dividends and income from property are taxed based on the tax year, the different rules for trading profits can confuse some taxpayers.

What is changing?

The proposed reforms will change the basis period for all unincorporated businesses to the end of the tax year, currently 5 April.

This will create the need for interim arrangements for businesses that do not currently have year-ends falling between 31 March and 5 April each year.

These businesses will potentially face a single, higher tax bill from their profits arising in the year-end falling in the 2023-24 tax year to 5 April 2024.

According to HMRC, businesses with a different accounting period end date to the end of the tax year:

  • Will need to apportion profits/losses.
  • May need to use provisional figures in their tax returns if the accounts and tax computations for later accounting periods in the tax year are not prepared before the tax return filing deadline (later amending their returns once figures are finalised).
  • The statutory rule that deems 31 March to be the 5 April in the first three years of a trade would be extended to apply to all years including the transition period and potentially also to property businesses.

Reliefs, allowances and tax band thresholds will remain unchanged and will not be pro-rated. This could also move some taxpayers into higher tax bands, while also reducing their ability to benefit from various annual reliefs and allowances.

In addition to the direct impact of the transitional arrangements, businesses with year ends that have not aligned with the tax year will have a much shorter time between when they generate profits and when the tax falls due, which could have cash flow implications.

What help is available?

Recognising the impact that this may have on taxpayers, HM Revenue & Customs (HMRC) is considering an election to allow businesses with higher profits, due to the change, to spread those additional profits equally over five years.

HMRC will also offer regular Time to Pay arrangements for those that need to spread the costs further.

Businesses will also be able to use all overlap relief accrued when they began trading during the transition year (2023-24). This would mean that businesses in this position will only have tax to pay on 12 months’ profits.

In the future, once these new rules are in place, new businesses will not generate overlap relief and there will be no special rules required for starting or ceasing trading or for a change in the accounting period end date.

For the many unincorporated businesses that already have year-ends aligning with the tax year (which includes those falling between 31 March and 5 April), nothing will change.

However, for those with year-ends that are not synchronised with the tax year, there are several considerations and careful tax planning may be necessary.

How we can help

These changes, when implemented, are likely to have a significant impact on unincorporated businesses, leading to substantial tax bills and costs without careful planning.

Worried you may be affected by these reforms? Find out how we can assist you.

Link: Basis period reform

How the penalty system for late tax submissions is changing

How the penalty system for late tax submissions is changing

Under new rules set by the Government, the system of penalties for VAT and Income Tax Self-Assessment (ITSA) are changing.

The new system of fines is aimed at tackling non-compliance by taxpayers who repeatedly fail to meet their obligations to provide returns and other information requested by HMRC. Those who make occasional and infrequent mistakes will be less likely to be penalised.

It will see the current system of automatic financial penalties removed and a new points-based system implemented, which will require taxpayers to incur a certain number of points for missed obligations before a financial penalty is issued.

The changes were initially meant to apply to VAT customers for accounting periods beginning on or after 1 April 2022, before being introduced later to ITSA customers with business or property income over £10,000 per year, who are mandated for Making Tax Digital (MTD) for ITSA, from the tax year beginning 6 April 2024, and for all other ITSA customers from the tax year beginning 6 April 2025. However, now the new rules for VAT will be delayed until 1 January 2023.

What will be considered a late submission?

The new rules are part of the ongoing implementation of MTD, which requires taxpayers to submit tax information digitally each quarter using compliant software.

Late submission under the new rules will be a failure to provide either a quarterly MTD update or an annual return on time.

However, it will not apply to other occasional submissions to HMRC, which will continue to be covered by the current penalty regime for the relevant submission.

How do the new late submission penalties work?

Every time you miss a submission deadline you will receive a point, which HMRC will notify you of on each occasion.

After you receive a certain number of points an initial financial penalty of £200 will be charged. The threshold that must be reached for a penalty to be issued is determined by how often a taxpayer is required to make their submission.

However, not only will a penalty be charged for that failure but every subsequent failure to make a submission on time. This means that those who continually fail to meet their obligations could face big fines.

The penalty thresholds are as follows:

Submission frequency Penalty threshold
Annual 2 points
Quarterly (including MTD for ITSA) 4 points
Monthly 5 points

The points are only applied to each type of submission you need to make, as you will only have points totals for each obligation.

That means if you miss two deadlines for separate submissions in the same month, you will be penalised separately for each submission type.

It is only where you regularly miss consecutive deadlines for a single type of submission that you will begin to accrue points that lead to a fine.

In general, if a taxpayer makes two or more failures relating to the same submission obligation in the same month, they will only incur a single point for that month.

This is to prevent a taxpayer reaching the points threshold too rapidly to be able to improve their compliance. However, there are exceptions to this rule, which can be found here.

Are late submission penalty points retained over time?

The points that are issued only have a lifetime of two years, after which they expire to prevent historic failures combining with occasional recent failures resulting in a fine. This period begins the month after the month in which the failure occurred.

Points will not expire when a taxpayer is at the penalty threshold. This ensures they must achieve a period of compliance to reset their points.

After a taxpayer has reached the penalty threshold, all the points accrued within that points total will be reset to zero when the taxpayer has met both of the following conditions:

  • A period of compliance; and
  • The taxpayer has provided all submissions due within the preceding 24 months (It does not matter whether these submissions were initially late).

Both requirements must be met before points can be reset. The periods of compliance are:

Submission frequency Period of compliance
Annual 24 months
Quarterly (including MTD for ITSA) 12 months
Monthly 6 months

If a taxpayer is at the penalty threshold and has achieved the period of compliance, but has not submitted outstanding submissions, they will remain at the penalty threshold and continue to be charged penalties for any further failures to make submissions on time.

There will be time limits after which a point cannot be levied. The time limits for levying a point depend on the taxpayer’s submission frequency and start from the day on which the failure occurred, as follows:

Submission frequency Time limit for levying a point
Annual 48 weeks
Quarterly (including Making Tax Digital) 11 weeks
Monthly 2 weeks

The time limit for HMRC to assess a financial penalty will be two years after the failure which gave rise to the penalty.

Can I appeal the issuing of a penalty point?

You can challenge a point or penalty issued by HMRC through its internal review process or via an appeal to the First Tier Tax Tribunal.

To appeal the issuing of points or a penalty you will need to be able to prove you had a reasonable excuse for missing a filing deadline, this could include bereavement or illness.

The appeal process will be the same as the appeal process against an assessment of tax for the relevant tax on which the penalty is based.

Here to help

Although this guidance covers the basics of these upcoming changes there are additional rules that may affect how penalty points are issued against you or your business.

If you are concerned about these changes or would like advice on remaining compliant with MTD for VAT and ITSA, please speak to our team today.

Link: Penalties for late submission

Accountants critical to the success of SMEs

Accountants critical to the success of SMEs

Small and medium-sized enterprises (SMEs) are the lifeblood of the country, accounting for 99.9 per cent of all businesses across the UK.

At the start of 2021, there were estimated to be 5.6 million UK private sector businesses.

But they acknowledge, according to a survey, that their operations would struggle to function efficiently without the assistance of accountants, particularly as COVID-19 has swept across the country.

Strategic guidance vital to SMEs

The survey has confirmed the importance of accountants to SMEs, rating the profession as the go-to business service as firms struggle with problems over the pandemic, Brexit and other areas like moving across to Making Tax Digital (MTD).

This is where the expertise of accountancy firms in the latest cloud accounting technology eases the burden on their clients.

The survey, commissioned by accountancy software supplier Sage, shows 91 per cent of SME owners rating accountants as an important part of their business operation, while 49 per cent are happy to approach them for strategic business guidance.

When asked what services they would go to when first starting a business, more than a third (34 per cent) said accountants would be the first port of call.

The survey also found:

  • Over a quarter (28 per cent) said Covid-19 had driven them to seek out the help of an accountant
  • A fifth (18 per cent) named Brexit as the driving factor. In fact, during the pandemic, over half increased their reliance on accountants
  • Sage also found that two-fifths (39 per cent) of SMEs name Making Tax Digital as the number one reason they sought accountancy services.

Named by small and mid-sized businesses as ‘critical’, the new study discovered a huge 91 per cent of SMEs use the services of an accountant, with half (49 per cent) using their services at least weekly.

Paul Struthers, MD, UK and Ireland, Sage, said: “Accountants play a critical role in accelerating this success and our research shows they are vital to the UK’s economic recovery.

“Our research shows accountants have an open door to become a de-facto strategic partner for their clients – this is an opportunity they must embrace.”

It is great to see that so many SMEs value the advice and services our profession offers. To find out how your business can benefit from our advice speak to us.

Link: SMEs name accountants as ‘number one’ service, report finds